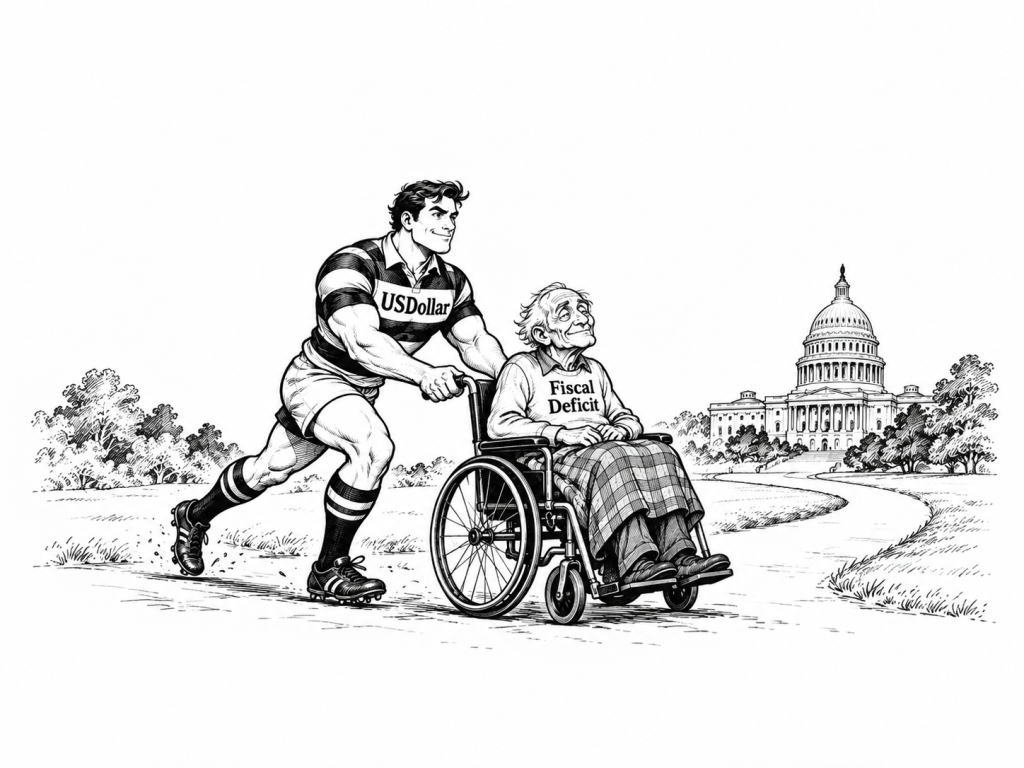
How can the U.S. dollar remain the world’s preferred safe haven when U.S. public finances are themselves becoming a growing source of concern?
The numbers are sobering. U.S. federal debt held by the public is projected at about 101% of GDP in 2026, rising to 120% by 2036. The federal deficit is projected at 5.8% of GDP this year and reaches 6.7% by 2036. By comparison, the euro area is projected to run a deficit of 3.6% of GDP in 2026.
Yet when markets panic, investors still reach for dollars.
Why?
Because the dollar itself appears to carry a value beyond the interest rate it earns.
Wenxin Du, Ritt Keerati and Jesse Schreger (2025) measure this through deviations from covered interest parity. Put simply, even after exchange-rate risk is hedged, investors have repeatedly been willing to pay a premium for access to dollar funding. Their research finds that this dollar “convenience” has remained strong since the global financial crisis.
A broader explanation comes from Jiang, Krishnamurthy and Lustig (2024). Their research shows that global demand for safe dollar assets is deeply intertwined with dollar borrowing and international financial conditions. They describe the global financial cycle as a dollar cycle.
The dollar is therefore not merely another currency backed by a sovereign balance sheet. It provides a service the global financial system is willing to pay for.
But something striking is happening underneath.
Du, Keerati and Schreger find a growing decoupling between “dollar privilege” and “Treasury privilege.” While the dollar itself remains unusually valuable as a funding and liquidity instrument, U.S. Treasuries have become less exceptional relative to other developed-market government bonds, particularly at medium and long maturities.
One important reason is supply. As U.S. government debt has expanded relative to the supply of other developed-market sovereign bonds, Treasuries have become less scarce. Investors therefore appear less willing to accept an unusually low yield simply for the privilege of owning them.
The world may still want dollars, while becoming less willing to finance the U.S. government at unusually favourable long-term yields.
Higher long-term Treasury yields therefore do not automatically imply a weaker dollar. They can reflect tighter monetary expectations, inflation risk or outright selling. But they can also reflect something more structural: an ever-growing supply of government debt that investors must be persuaded to absorb.
None of this means fiscal deterioration is irrelevant. Could it eventually damage the dollar’s privilege too?
Certainly.
But replacing the dollar requires more than disliking U.S. fiscal policy. The yen and Swiss franc can also behave as safe havens in periods of stress, but neither matches the dollar’s combination of scale, liquidity, reserve use, collateral value and global financing reach.
For now, the slightly paradoxical conclusion may be this:
The dollar may be safer than the debt behind it.