A misconception we often encounter in conversations with prospective investors is that returns in currencies should be viewed in much the same way as returns in equities or bonds.
They should not.
In traditional asset classes, part (or all!) of the return can come simply from owning the market. Equities, bonds and real estate can all rise in value over time. That market return is beta: the return you receive for choosing to take market exposure.
Alpha is different. Alpha is the return generated beyond that market exposure — and therefore depends on skill.
Currencies are different because there is no broad currency market that simply rises over time. Every currency is priced against another currency. If one appreciates, another depreciates. There is no equivalent of the long-term equity-market tailwind.
Positive returns from active currency management therefore have to be earned: through selection, timing, position sizing, risk management and disciplined execution.
And this leads to another important characteristic of currency alpha: it is portable.
Because currency returns have no correlation with equities and bonds, that alpha can be introduced into an existing mixed portfolio without simply adding more of the same market risk.
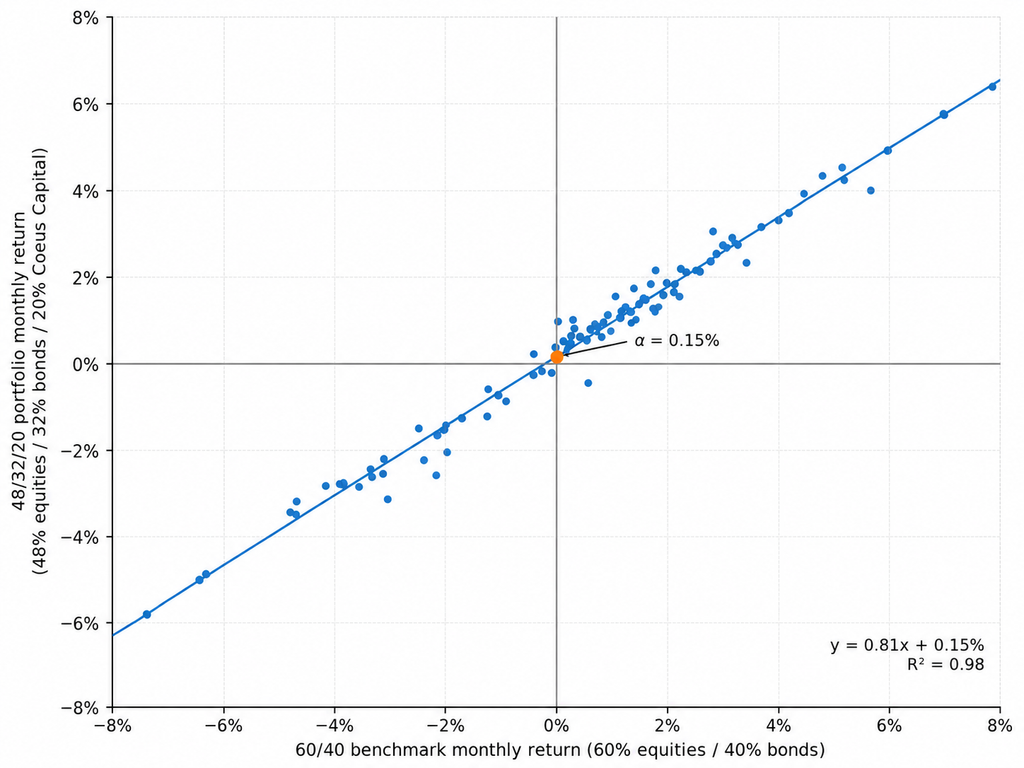
The illustration below shows exactly this. We compare a traditional 60% equity / 40% bond portfolio with a portfolio consisting of 48% equities, 32% bonds and 20% Coeus Capital.
Each dot represents one month since March 2018. The regression line crosses the vertical axis above zero. In other words, after accounting for the portfolio’s market exposure — its beta — a positive return remains.
That intercept is alpha. And that is what we mean by portable alpha.